
Automatic Bank Reconciliation in S/4HANA: Designing for Hands-Off Matching
Automatic bank reconciliation in SAP S/4HANA: bank statement setup, interpretation algorithms, search strings and reprocessing rules for hands-off matching.

Bank reconciliation is the close task everyone wants automated and few teams actually trust. In SAP S/4HANA, the building blocks are mature: electronic bank statements, interpretation algorithms, search strings, reprocessing rules and bank account master data. The difference between a reconciliation that runs itself and one that lives in spreadsheets is almost always design, not software.
This article walks through how automatic bank reconciliation works in S/4HANA, how to design it so most items clear without touching them, and how to run the exceptions without slowing month-end close.
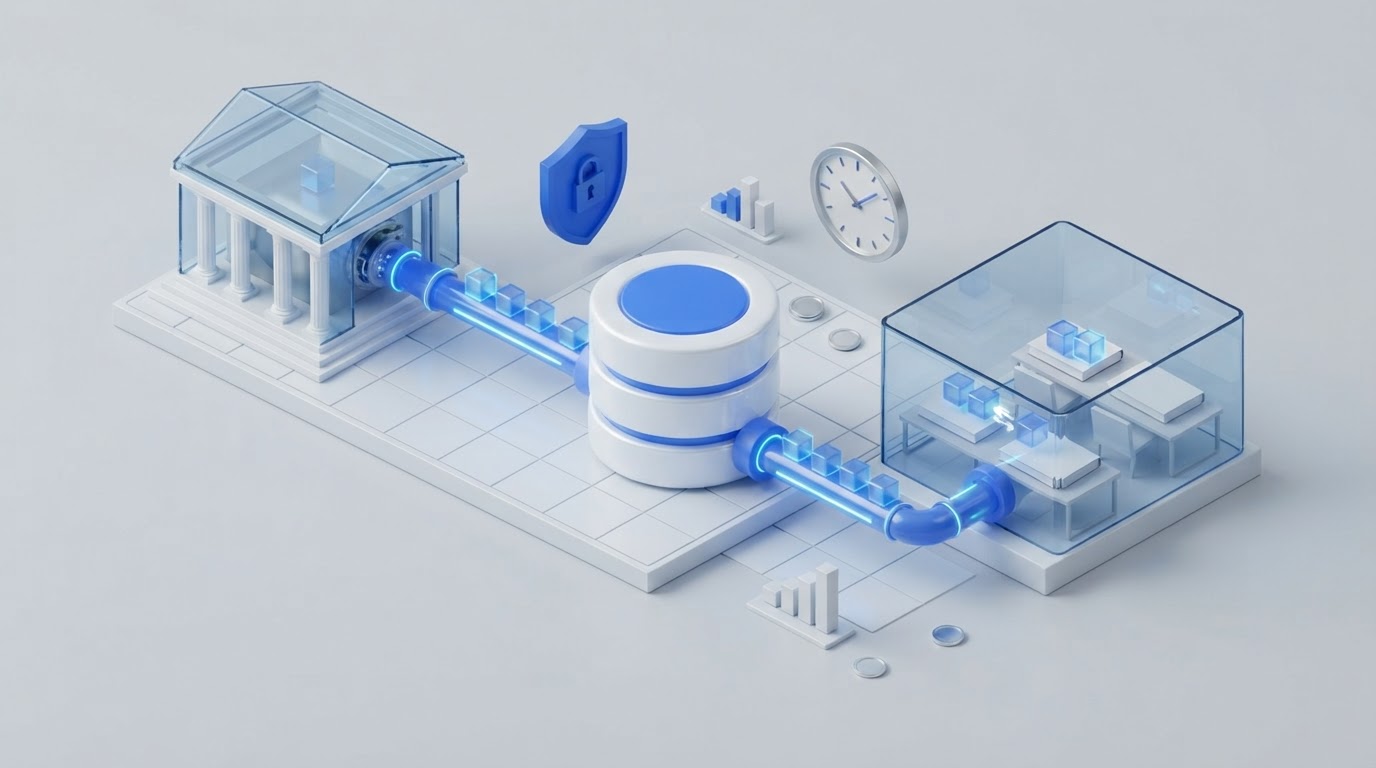
The flow in one picture
- The bank sends a statement file, typically CAMT.053, MT940 or BAI2, depending on the bank and country.
- S/4HANA imports the file and creates a bank statement with one line per transaction.
- Each line is mapped to a posting rule through its external transaction type, such as incoming transfer, outgoing check or bank fee.
- An interpretation algorithm and, if configured, search strings try to identify the open item to clear: a customer invoice, a vendor payment or a GL clearing item.
- The system posts to the general ledger (bank account against a clearing account) and, when it finds a match, clears subledger or GL open items.
- What does not clear goes to post-processing.
The objective is simple: steps 3 to 5 should handle the large majority of lines, and step 6 should be short and owned.
The account design that makes reconciliation possible
A common and robust design uses one main bank account plus clearing subaccounts per house bank account, for example:
- Main bank account: mirrors the bank balance.
- Outgoing payments clearing: credited by the payment run, cleared when the bank statement shows the debit.
- Incoming payments clearing: used when receipts are posted before or after the statement.
- Checks clearing: cleared when issued checks are presented.
- Bank fees and interest: posted directly from the statement.
With open-item management on the clearing accounts, anything left open is by definition unreconciled. That turns reconciliation into an open-item review instead of a balance comparison.
Bank account master data in S/4HANA
In S/4HANA, bank accounts are master data managed in Bank Account Management, typically through the Fiori app Manage Bank Accounts, and linked to house bank accounts used in configuration. Basic bank account management is part of the core; advanced cash management capabilities depend on licensing and scope. Clarify that early so the design does not assume functions you have not licensed.
Practical points:
- Keep one owner for bank account master data and a change process, ideally with approval.
- Align bank account IDs, house bank IDs and GL accounts with a clear naming convention.
- Make sure each account carries the currency and the GL accounts you will reconcile.
Configuring the electronic bank statement
The global settings for electronic bank statements define the logic. The main elements are:
Account symbols and posting rules
Account symbols represent the GL accounts involved (bank, clearing subaccounts, fees). Posting rules combine them into postings: for example, “outgoing transfer” debits outgoing payments clearing and credits the main bank account, and clears the open item on the clearing account.
External transaction types
Each bank code in the file, such as a BAI2 type code or a CAMT bank transaction code, is mapped to a posting rule. Incomplete mapping is one of the most frequent reasons lines fail. Collect real statement files from every bank and every account before go-live, not only test samples.
Interpretation algorithms
The interpretation algorithm tells the system how to read the note to payee and reference fields to find what to clear. Commonly used options include standard interpretation (001), check-number based algorithms for outgoing checks (the 011–013 range), and document-number or reference-number searches (020, 021). The right algorithm depends on what your customers and banks actually send.
Search strings
Search strings (configured with transaction OTPM) use patterns to extract information from free-text fields, such as an invoice number, a payment run reference or a customer number, and map it to the field the algorithm uses. This is where automation rates typically jump: banks and customers rarely put references exactly where SAP expects them, and search strings bridge the gap.
Design for automatic clearing of incoming payments
Incoming payments are where most manual work hides. To improve matching:
- Ask customers for structured references. Put the invoice number or a payment reference prominently on invoices and remittance instructions.
- Use payment advice when available. Remittance data allows the system to clear several invoices from one payment.
- Define tolerances. Customer and GL tolerances allow small differences, such as bank charges deducted by the payer, to be cleared and posted automatically within policy.
- Use search strings for real patterns. Analyze three months of unmatched lines and build search strings from the most frequent formats.
- Evaluate intelligent matching. SAP offers machine-learning based cash application options. Availability depends on edition and licensing; consider them after the rule-based basics are solid.
Post-processing without chaos
Some lines will always need a person. S/4HANA offers several tools:
- FEBAN (Edit Electronic Bank Statement) for classic post-processing.
- Reprocess Bank Statement Items in Fiori, to assign open items, post differences and complete clearing.
- Reprocessing rules (managed in Fiori), which let you define rules for recurring items, such as a known fee or a regular transfer, so they post automatically next time.
- Bank statement monitoring in Fiori, to see which accounts received statements, which are complete and which still have open items.
An operating model that works:
- Daily: statements import automatically; the treasury or AR team reviews exceptions the same day.
- Rule feedback: each recurring manual item becomes a candidate for a search string, a reprocessing rule or a tolerance.
- Weekly: review open items on clearing accounts by age.
- Close: every clearing account is either zero or explained by items with an owner and an expected clearing date.
Common mistakes
- Testing with clean sample files. Real files have odd references, reversals and bank-specific codes. Test with production-like data from every bank.
- No open-item management on clearing accounts. Without it, you reconcile balances, not items.
- One giant suspense account. Unidentified receipts parked on a single account without owners grow quickly. Use a clear process to identify and clear them.
- Ignoring statement completeness. A missing statement day breaks the balance chain. Monitor sequence and opening balances.
- Leaving automation to IT. AR, AP and treasury know the patterns. They must own the rules.
FAQ: bank reconciliation in S/4HANA
Which bank statement format should we use?
Use the format your banks support best. CAMT.053 is increasingly common because it is structured XML with richer remittance information, while MT940 and BAI2 remain widely used. Confirm format variants with each bank.
Is Bank Account Management mandatory?
In S/4HANA, bank accounts are maintained as master data through Bank Account Management. Basic functions are part of the core; advanced cash management features depend on licensing.
What is a realistic automation target?
It depends on banks, customers and remittance quality. Measure your baseline in the first weeks, then improve it with search strings, reprocessing rules and tolerances. Avoid promising a number before you have analyzed real data.
Can we keep manual bank statements for some accounts?
Yes, manual bank statements remain possible for low-volume accounts, but electronic statements should be the default wherever the bank supports them.
Final thought
Automatic bank reconciliation is a design exercise: clean account structure, complete transaction type mapping, the right algorithms, and a feedback loop that turns every repeated manual item into a rule. Do that, and the daily reconciliation becomes a short exception list.
Contact advisory if you want a practical review of your bank reconciliation design in S/4HANA.